Part of the Shmor.ai network · Free, independent insurance guides for the UK, US & Europe

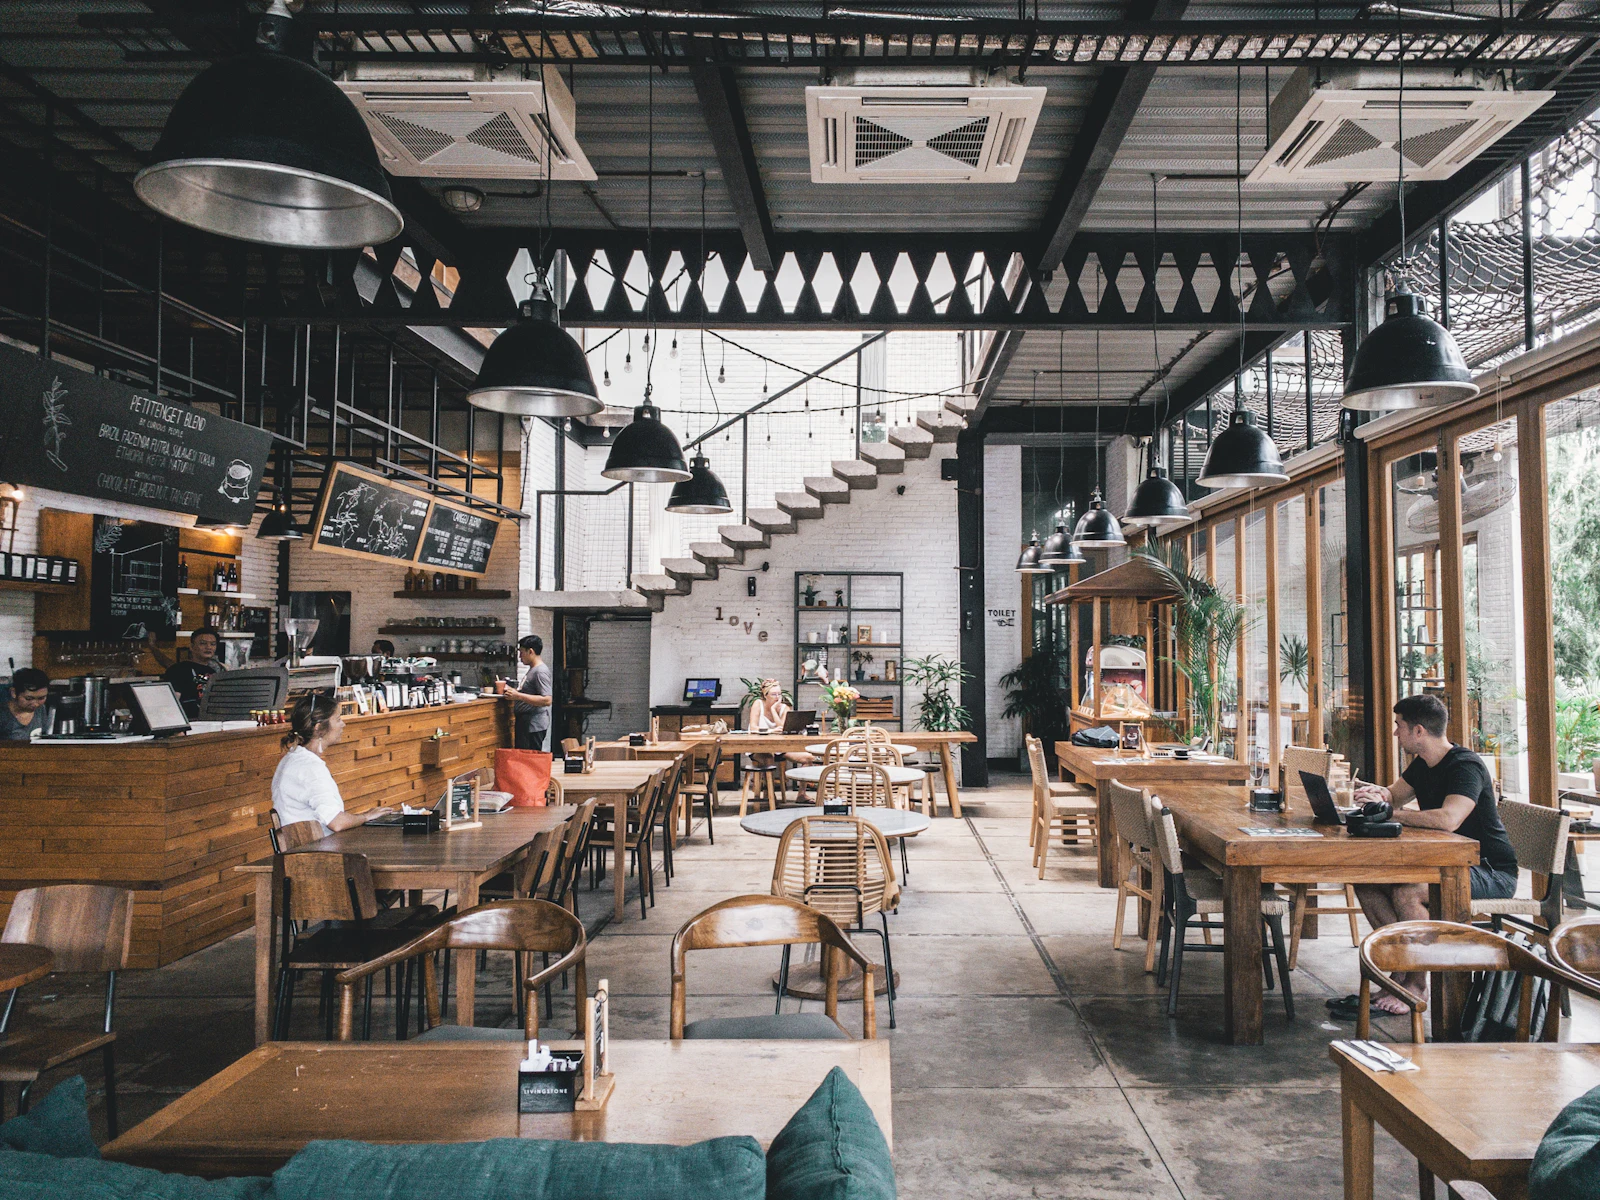
Rustic café interior with wooden tables ready for customers

Commercial · Liability

Public liability and general liability insurance

If a customer trips over your cable, or you damage a client’s floor while working, public liability (called general liability in the US) pays compensation and legal costs. It’s the cover clients ask for most.

Photo: Shawn on Unsplash

At a glance

Ref. COM-PL
Covers
Injury to members of the public and damage to their property caused by your business, plus legal costs.
Who needs it
Shops, cafés, tradespeople, event organisers, anyone who meets clients or works on their premises.
Legal requirement
Not by law in the UK or most US states, but often required by contracts, venues and councils.
Typical limits
UK: often £1m, £2m, £5m or £10m. US: often $1m per occurrence / $2m aggregate.
Often paired with
Products liability, employers’ liability or workers’ comp.

Public liability at a glance

Usually covered

  • Injury to customers, visitors and the public
  • Damage to third-party property (e.g. a client’s home)
  • Legal defence costs and compensation
  • Products liability, if included: harm caused by products you sell or make

Usually not covered

  • Injury to your own employees (that’s employers’ liability or workers’ comp)
  • Damage to your own property or tools
  • Financial loss from advice (that’s professional indemnity)
  • Deliberate acts and contractual penalties
  • Work on certain hazardous sites without declaration

Common add-ons

  • Products liability
  • Contract works
  • Tools and equipment
  • Legal expenses

General guide only. Cover varies by insurer and policy: the policy wording and key facts document decide what you’re actually insured for.

Public liability vs general liability

The idea is the same on both sides of the Atlantic. In the UK, public liability is a standalone cover, often sold with products liability. In the US, commercial general liability (CGL) is broader: it typically includes bodily injury and property damage, products and completed operations, and “personal and advertising injury” such as defamation. US small businesses often buy it inside a BOP.

How much cover do you need?

Choose a limit that reflects the worst realistic claim and what your contracts require. Councils, venues, construction sites and large clients often set a minimum. A serious injury claim can be very expensive, so don’t pick the lowest limit just because it’s cheapest; the difference between limits is often modest.

Products liability

If you make, sell, repair or import products, you can be liable if one causes injury or damage. Importers and own-brand sellers can carry the same responsibility as manufacturers. Check that products liability is included and whether it covers sales to the US and Canada, which some policies exclude or limit.

Certificates of insurance

Clients often ask for proof of cover. In the UK, your insurer or broker can provide a policy schedule or certificate. In the US, a certificate of insurance (COI) is standard, and clients may ask to be named as an additional insured, which extends your policy to cover them for claims arising from your work.

Last updated: 15 October 2026

Frequently asked questions

Is public liability insurance a legal requirement?
Not in the UK or for most US businesses. But you may not get work without it, because clients, venues and landlords commonly require it.
Does public liability cover my employees?
No. Injuries to employees are covered by employers’ liability (UK) or workers’ compensation (US).
Do I need it if I work from home?
If clients visit you, or you work at clients’ premises, it’s worth having. Your home insurance usually won’t cover business visitors. See home business insurance.

What do you want to insure?